Tag: elections
Asset Allocation Bi-Weekly – The Third-Year Charm: Why Gridlock Sets the Stage for Market Growth (November 2, 2026)
by Thomas Wash | PDF
Every political cycle arrives wrapped in apocalyptic campaign ads branding the upcoming election as “the most consequential of our lifetime.” Yet while political strategists focus on polarization, we are watching a far more concrete signal: stock market performance over the four-year presidential cycle.
From 1930 to 2023, the third year of a president’s term generated the strongest equity returns of the four-year cycle, driven largely by especially outsized gains in the stretch immediately after the midterm elections. That pattern is especially pronounced under second-term Republican administrations, when post-midterm rallies gain significant momentum, which could point to a strong 2027.
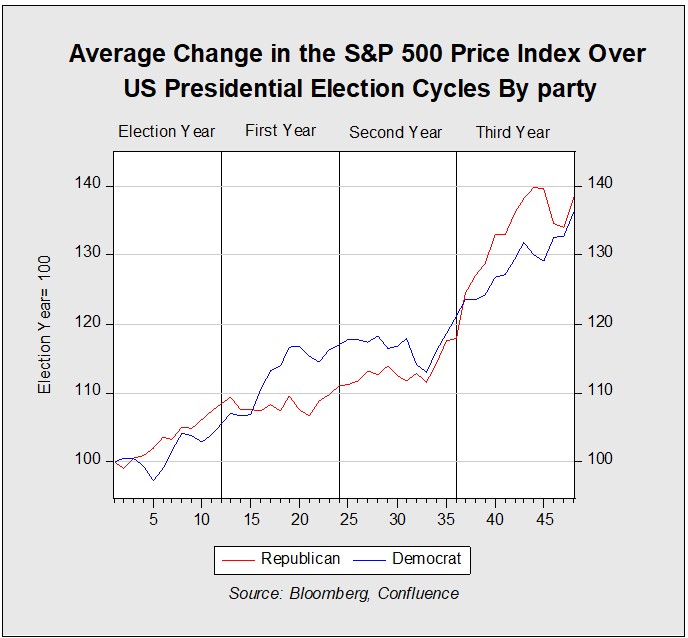
Measured from the start of the election year, when markets begin pricing in political shifts, through the third year of a term, stock returns under Republican presidents have slightly outpaced those under Democratic ones, with the S&P 500 rising 38.3% compared to 36.2%. What makes this outperformance particularly striking is that markets under Republican presidents typically underperform in their first two years, only to rally sharply in the third.
The market’s strong third-year performance is driven primarily by expectations of greater policy predictability. Historically, the party that lost the previous presidential race enjoys a midterm resurgence as rallying a frustrated base is far easier after a defeat. When this opposition party gains control of Congress, it creates legislative gridlock, tempering the administration’s most aggressive policies and forcing both parties toward consensus.
The latest Polymarket odds show more than an 80% probability that Democrats will take control of the House in the upcoming midterms. While prediction markets also favor a Democratic Senate takeover, polling data suggests those races may be much closer. Divided government — whether Democrats win one chamber or both — would likely bring gridlock after two years of unified Republican control of the White House and Congress.
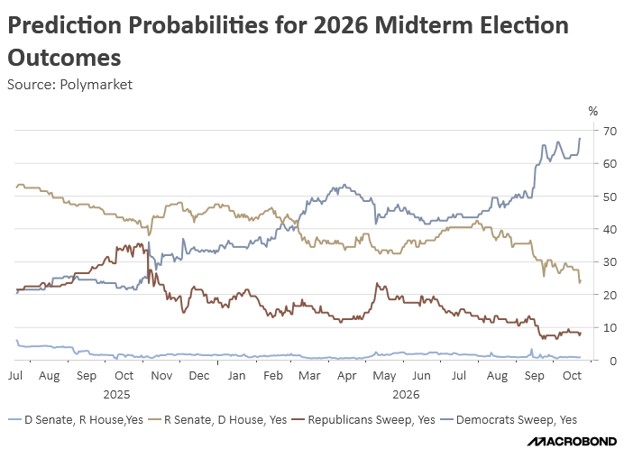
Historically, shifts in congressional control have served as a vital check on executive and legislative overreach. For example, the 2022 midterm elections created a split Congress, reining in Democratic expansionary spending plans and easing investor worries over out-of-control federal deficits. Similarly, the 2018 midterms produced a divided government, forcing both parties to the negotiating table in 2020 and resulting in bipartisan economic relief packages for businesses and families during pandemic lockdowns.
Depending on whether Democrats take control of one or both houses of Congress, changes in fiscal and foreign policy could provide a welcome boost to markets. Democratic control of the House, in particular, would put the spotlight on the federal deficit. Because neither party would hold total control, both sides could be forced to compromise to pass a budget and avoid a government shutdown. While this budget fight may trigger political brinkmanship, it should ultimately yield a more concrete framework to curtail spending.
On the other hand, a Democratic sweep of Congress would pose a greater challenge to the executive branch, forcing the White House to coordinate more closely with lawmakers. While this legislative process is rarely pretty, both sides should ultimately be able to align on a clearer strategy on national security, trade, and AI governance. By balancing power between the executive and legislative branches, divided government tends to reduce market uncertainty by preventing sudden, unilateral policy shifts and fostering greater transparency.
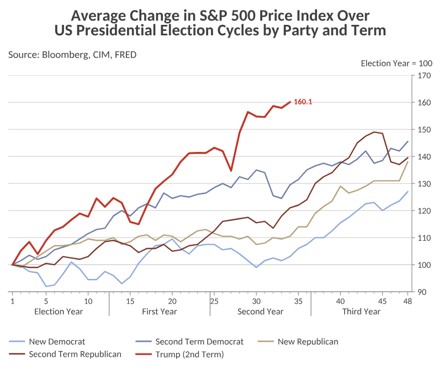
Markets typically perform better in a president’s third year because policy becomes far more predictable — a dynamic that could prove particularly beneficial heading into 2027. While data from George W. Bush’s presidency was distorted by the start of the subprime mortgage crisis in 2007, second-term Republican administrations have historically delivered the strongest third-year market gains. That same pattern could emerge this time around, particularly since fluctuating trade, fiscal, and foreign policies have created price volatility and complicated efforts to deploy capital beyond the AI sector — pressures that more gridlock could help ease.
Ultimately, the prospect of a more balanced Congress forcing bipartisan cooperation should serve as a key market catalyst. Fewer abrupt policy shifts would make it easier for companies to plan for the future. This newfound clarity — paired with lower interest rates driven by easing geopolitical tensions and better fiscal policy — should allow businesses to capitalize on the AI buildout and expand investment across the broader market.
Don’t miss our accompanying podcasts, available on our website and most podcast platforms: Apple | Spotify
Bi-Weekly Geopolitical Podcast – #54 “The US Presidential Election: Foreign Policy Implications” (Posted 10/7/24)
Bi-Weekly Geopolitical Report – The US Presidential Election: Foreign Policy Implications (October 7, 2024)
by Daniel Ortwerth, CFA and Thomas Wash | PDF
History shows that, despite the promises made as candidates, United States presidents display remarkable foreign policy consistency from one administration to the next. While often distinguishing themselves in the realm of domestic policy, the imperatives of national security tend to force the hands of presidents into choices that change very little (if at all) with party affiliation. In other words, foreign policy tends to be remarkably consistent.
Nevertheless, foreign policy typically provides at least some room for maneuver, and presidents use this wiggle room to pursue their priorities as circumstances permit. Often these priorities are different from one candidate to the next. With the presidential election looming in November, we need to understand these differences and their investment implications.
This report analyzes how US foreign policy might look in a new term for former President Donald Trump, the Republican candidate, and in an initial term for Vice President Kamala Harris, the Democratic candidate. It begins with a characterization of the two candidates according to the main American foreign policy traditions. It considers the kinds of cabinet members they will probably choose to fill the rosters of their foreign policy teams, and it culminates with a review of their priorities as we know them. As always, we conclude the report with implications for investors, in this case as they differ between the two candidates.
Don’t miss our accompanying podcasts, available on our website and most podcast platforms: Apple | Spotify
Asset Allocation Bi-Weekly – #126 “Presidential Cycles and Stock Performance” (Posted 9/30/24)
Asset Allocation Bi-Weekly – Presidential Cycles and Stock Performance (September 30, 2024)
by the Asset Allocation Committee | PDF
As the November elections approach, there has been significant debate over which presidential candidate — former President Donald Trump or Vice President Kamala Harris — would be better for US equity markets. Both candidates have made bold promises about their plans to boost national prosperity. Trump has vowed to reduce burdensome regulations and deliver tax cuts to households and businesses, while Harris has advocated tax incentives for homebuilders to boost supply, address housing affordability, and help bring down the cost of living.
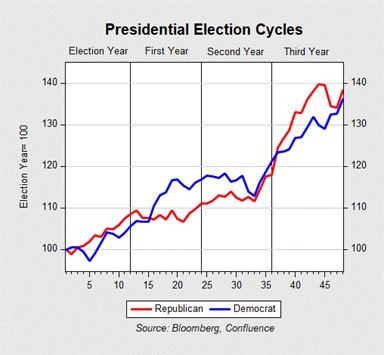
While both candidates have reasonable policy goals but differing policy prescriptions, their overall impact on investor portfolios may likely be similar. Contrary to popular belief, presidents have had limited influence on equity returns. An analysis of the S&P 500’s performance from 1930 to 2023 shows that stocks have provided a return of about 30%, on average, over a typical four-year term, with the returns under Republican presidents only slightly topping the returns under Democrats.
The key reason for the similar outcome is that presidents are often constrained by the conditions they inherit. These include the state of the economy, the composition of Congress, and monetary policy. While a president may have some influence over these factors, their ability to shape them is largely determined by the circumstances they receive in the election. A popular president may secure a Congress with a substantial majority, enabling them to pass key legislation and select their preferred candidate as the chair of the Federal Reserve. That said, such a strong majority with unified government is not the norm.
Historically, stock market performance during US presidential election years has been influenced by the broader economic trends in place at the time. While equities under Republican administrations often outperform Democratic administrations in election years, Democrats close the gap over the first and second years following the election. This tendency is largely attributed to the economic conditions that new Democratic presidents frequently inherit. Democrat victories often coincide with economic downturns, allowing for stimulus measures that eventually help asset prices recover. Conversely, Republican administrations tend to benefit from a “continuity rally” following the positive economic performance in the year prior to the election.
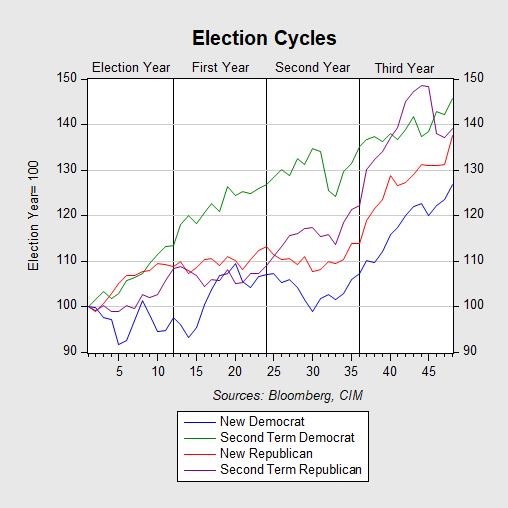
During their first year, Democrats tend to get off to a better start but ultimately suffer the same fate of stagnation. New presidents often enjoy greater flexibility to provide more fiscal and monetary stimulus, helping to improve the economy. This can boost market optimism. By their second term, however, leaders typically face diminished support, making it more difficult to pass significant legislation in the first year. This predictability, while not without its challenges, can often be positive for equities.
In contrast, new Republican administrations often inherit a tougher policy environment in the first year, marked by higher inflation and tighter monetary policies. Historically, average policy rates have been roughly three times higher under Republicans (7.8%) than under Democrats (2.4%); inflation rates have also been higher (5.1% vs. 3.0%, respectively). With the exception of the Nixon-Ford administration, second-term Republican presidents generally fare better than their first-term counterparts, for similar reasons as second-term Democrats.
In the following year, midterm elections significantly shape market sentiment as Congress goes through a reshuffle. Democrats often get the worst of it and lose an average of 28 House seats and 3 Senate seats, while Republicans typically lose 21 House seats and 1 Senate seat. This shift in Congress leads to concerns about the future of recent policy decisions by Democrats, creating uncertainty as markets gauge the potential impact on future policy. Conversely, Republicans’ relative successes in midterms often signal confidence in the president’s leadership, boosting expectations of policy continuity and benefiting equities.
The third year of a presidential term, leading up to the election, often sees strong economic performance for both parties. This trend can partly be attributed to political gridlock, which limits major legislative changes and creates a stable environment favorable to the stock market. While brief market dips may occur, particularly under Democratic presidents due to budget negotiations that introduce uncertainty, these downturns are typically followed by a rebound, reflecting investors’ confidence in the broader economic trajectory.
In sum, presidents are often labeled as either pro-market or anti-market, but research suggests that their influence on the economy and stock market is often overestimated. A president’s first year is typically focused on addressing ongoing economic challenges. The second year can be more uncertain, as the composition of Congress is solidified. The third year often sees a boost in the market because of investors’ preference for political gridlock. For investors, this election cycle highlights the importance of focusing on broader economic factors, monetary policy, and the composition of Congress. While the presidency can play a role, it’s essential to consider the bigger picture.
Bi-Weekly Geopolitical Podcast – #50 “The EU Parliamentary Elections: New Strength for the Right” (Posted 7/1/24)
Bi-Weekly Geopolitical Report – The EU Parliamentary Elections: New Strength for the Right (July 1, 2024)
by Patrick Fearon-Hernandez, CFA | PDF
In early June, voters across Europe cast ballots for their representatives to the European Parliament, an institution likely unfamiliar to most Americans. Even among the few who may know of it, we suspect many don’t really understand it or other top European Union institutions. In this report, we offer a primer on the main EU decision-making bodies and how they work together. We also review the results of the early June parliamentary elections, in which right-wing populists significantly increased their strength in the legislature, largely at the expense of leftists. We examine the implications at the EU level and within key EU countries. We wrap up with a discussion of the investment ramifications.