


Author: Rebekah Stovall
Asset Allocation Weekly – Intellectual Property Takes Over Fixed Investment (August 13, 2021)
by the Asset Allocation Committee | PDF
It’s probably no surprise to anyone that information processing has become a bigger and bigger part of the economy over the last several decades. By now, we’ve all gotten used to seeing new kinds of computers and telephones every year, and we’ve struggled with learning new software programs at home or at work. Whether you call it the “digital economy” or the “knowledge economy,” what few people realize is that it’s about to reach an important milestone in the data on U.S. gross domestic product (GDP). Therefore, this may be a good time to explore some of the investment ramifications of the trend.
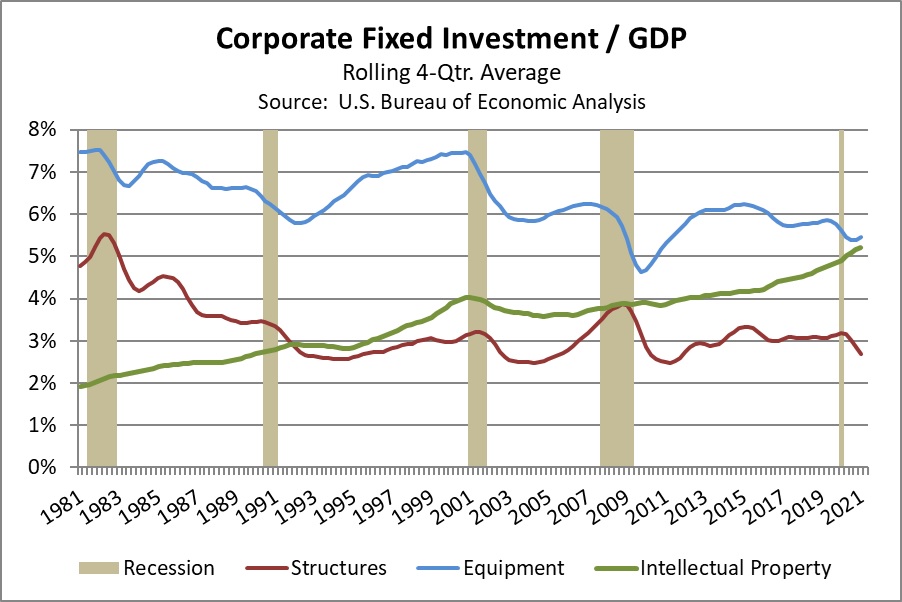
In the U.S., private investment spending currently accounts for about 17.5% of total GDP, but the category naturally includes a lot of subcomponents. Housing and corporate inventory investment are only a small part of the total. The biggest component of the category is “nonresidential fixed investment,” which is often referred to as “corporate” fixed investment and makes up roughly 13.5% of GDP. As late as the 1990s, corporate fixed investment was dominated by spending on machinery, equipment, and structures. Investment in intellectual property—mostly spending on research and development—was a much smaller part of the category. The difference now is that spending on intellectual property has exploded, mostly because of a surge in software investment. Overall, corporate fixed investment has grown at an average annual rate of 7.6% over the last four decades (including price changes), with software investment rising at a rate of 10.9% and R&D investment rising at a rate of 7.1%. As a result, intellectual property is on the verge of becoming the biggest component of corporate fixed investment.
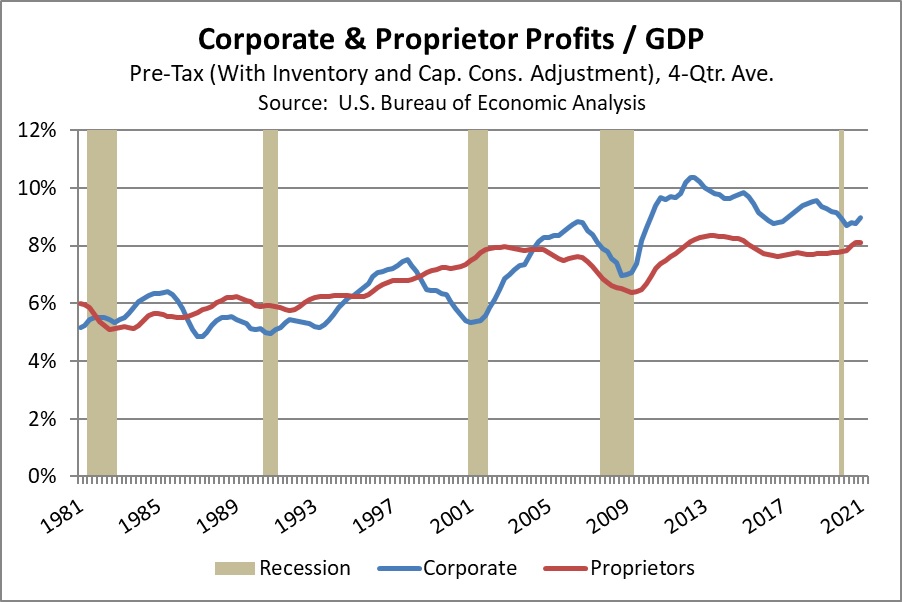
The implications of this evolution are enormous. In economic terms, the marginal cost of selling an additional software package or leveraging the R&D behind it can be minimal. In addition, digital products and software can have big spillover effects, in the sense that they can give value to customers beyond the core service the software is designed for. A good example of this is the “network effect” when the customer gets greater value from joining a social media network when the network has more people. The low cost of selling additional units and the incentive to capture spillover value means that digital businesses have a huge incentive to grow their network and become as big as possible. The growing dominance of intellectual property in the economy is probably one reason why corporate profits as a share of GDP have risen starkly over the last several decades (see chart below). Note, however, that those businesses’ enormous size is now generating concerns that they are stifling competition, which could lead to tougher antitrust regulation around the world.
Naturally, investors are attracted to the increasing size and profitability of firms that produce software or can efficiently leverage their digital R&D. In addition, as other businesses continue learning how to boost their productivity using big data, data management, data analysis, and artificial intelligence, they are probably less likely to cut their intellectual property investment in times of recession. Indeed, intellectual property investment continued to rise throughout the Great Financial Crisis of 2008-2009 and the recession in 2020 due to the coronavirus, as shown in the first chart above. From another perspective, the growth rate of inflation-adjusted intellectual property investment has had a standard deviation of just 5.2% since 2000, which is modestly lower than the standard deviation of 5.8% for overall GDP and dramatically lower than the average deviation of 13.9% for equipment and 14.4% for structures. In sum, intellectual property investment is much more stable than investors realize, so there is a good economic reason why digital technology and software firms are increasingly being seen as “defensive.” In many environments, we favor this sector for offering an attractive combination of good prospects with relatively less sales volatility than investors perceive.
Weekly Energy Update (August 12, 2021)
by Bill O’Grady, Thomas Wash, and Patrick Fearon-Hernandez, CFA | PDF
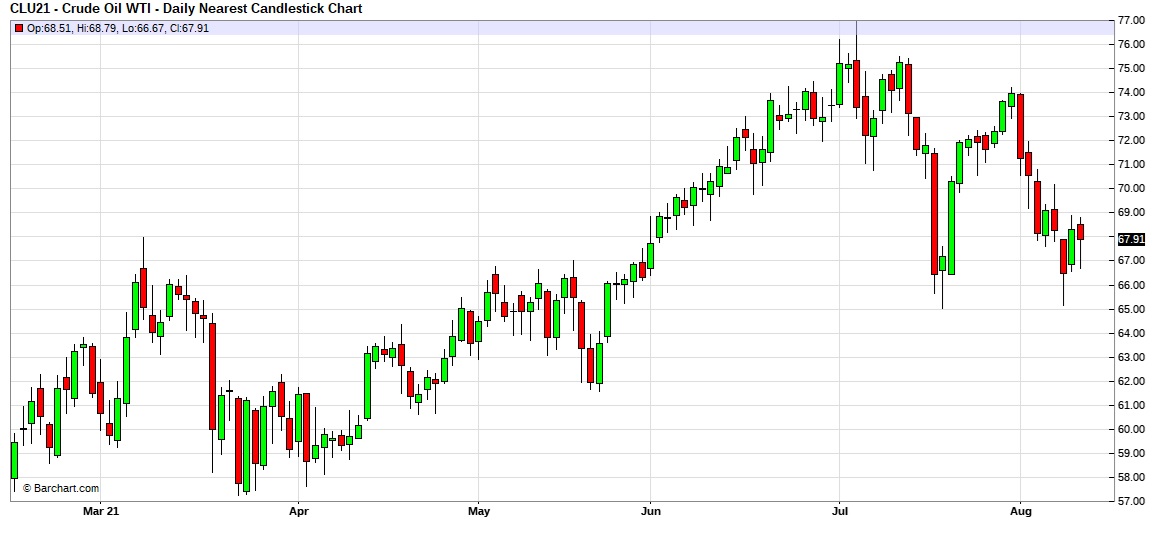
Oil prices remain depressed, with $67 acting as support.
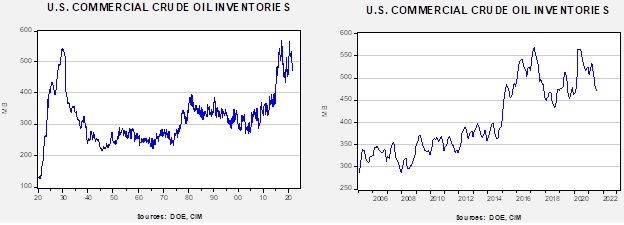
Crude oil inventories unexpectedly fell 0.4 mb compared to the 2.0 mb draw forecast. The SPR was unchanged this week.
In the details, U.S. crude oil production rose 0.1 mbpd to 11.3 mbpd. Exports rose 0.8 mbpd, while imports were unchanged. Refining activity rose 0.5%.
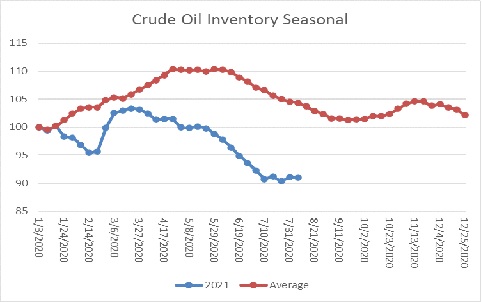
This chart shows the seasonal pattern for crude oil inventories. We are well into the summer withdrawal season. Note that stocks are well below the usual seasonal trough seen in early September. A normal seasonal decline would result in inventories around 550 mb. Our seasonal deficit is 69.2 mb. Since early July, inventory levels have stabilized; as the chart indicates, seasonal inventory stabilization usually occurs in September, so if this pattern continues, the seasonal deficit should narrow.
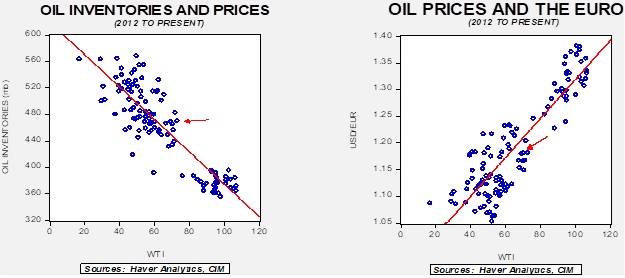
Based on our oil inventory/price model, fair value is $61.67; using the euro/price model, fair value is $62.50. The combined model, a broader analysis of the oil price, generates a fair value of $61.76. The weaker EUR has started to affect the model forecast, putting all the models’ fair value calculations well below the current price.
Market news:
- Headlining this week’s market news is the IPCC report that suggests global temperatures are rising rapidly and the odds of climate destabilization are rising. One element of this destabilization is wildfires, which are punishing Europe and the Western U.S. Although devising new ways to limit methane and CO2 emissions will help limit the damage, in reality, much of the damage is already in place and even moving to zero emissions today will not likely prevent continued warming. So, policymakers have to not only move on alternative energy but also climate mitigation.
- The Senate passed a $1.2 trillion infrastructure package, which has some measures to address both mitigation and emissions control. The bill includes:
- $73 billion for grid upgrades and increased powers to FERC for power lines. One of the problems facing the country is that alternative energy production usually exists in low population areas and long power lines are required to move the “juice” to where it is needed, which are urban areas. However, building these lines is difficult because of local opposition, which is sometimes funded by urban utilities that don’t want the wind or solar competition.
- $6 billion for nuclear energy which is designed to extend the life of existing facilities. Although nuclear power is controversial, it is clearly emission-free power.
- $7.9 billion for funding clean energy initiatives, with an emphasis on battery manufacturing and recycling.
- $15 billion for electrification, with half going to funding EV charging stations.
- $8.5 billion for carbon capture and sequestration.
- $1.0 billion for clean hydrogen.
- An initiative but no funding for orphaned oil and gas wells.
- Executive order for 50% zero emissions vehicles by 2030.
Overall, the bill mostly supports big electricity. Distributed power didn’t get much support. In addition, there was a clear focus on building the infrastructure for auto electrification.
- Politics by its very nature leads to disingenuous behavior. One of the primary functions of the political process is to determine who bears the cost of adjustment with any policy action. Politicians always attempt to hide the costs from those who will bear them, or somehow argue that those stuck with the “bill” deserve the pain. Acknowledging the fact that allocation costs and benefits are simply part of the political process isn’t enough; political operators also have to justify their actions. After all, elections are popularity contests and being difficult makes one unpopular. With that being said, we watched the recent actions by the administration with some degree of astonishment. From the outset, as we have discussed in earlier reports, the administration has taken the path of acting on climate change. The administration has enforced several actions, including restricting drilling on federal lands, discouraging the finance industry from supporting the fossil fuel industry, and threatening legal action against polluters, which are mostly oil and gas companies. If the goal is to reduce CO2 emissions, rising energy prices are an unavoidable consequence. However, this action conflicts with the popularity contest nature of elections. And so, yesterday, National Security Director Sullivan criticized OPEC+ for not increasing oil production enough to lower oil and gas prices.
- This criticism is epic in its disingenuousness. Oil prices are up, in part, because the administration is reducing land available for oil and gas production and is starving the industry for investment funding. These actions were taken due to climate concerns. Pushing OPEC+ to boost output conflicts with the goal of addressing climate change.
- The U.S. is rapidly abandoning involvement in the Middle East. The U.S. troop withdrawal is leading to the Taliban retaking control in Afghanistan, which could destabilize parts of the region. We are also reducing our involvement in Iraq to mere training of security forces. Again, there are clearly justifiable reasons for reducing involvement in the region. We can see peak oil demand on the horizon, and we should be focusing on great power competition with China. Freeing up resources for this outcome makes sense. But you can’t expect OPEC+ to listen when you have made it clear that most of the major oil-producing nations are no longer important.
- However, we do note that Saudi Aramco (2222, SAR, 35.25) has indicated it will raise production in a bid to lift market share. There isn’t any indication that it will move aggressively to lower prices.
- We also note that oil prices have been weakening recently on concerns that the delta variant will reduce oil demand.
- The administration is also calling on the FTC to investigate gasoline “price gouging.” I have covered energy since 1989 and have seen this sort of call occur numerous times. It’s a bit like “rounding up the usual suspects.”
- Overall, we don’t think this jawboning will have any effect. The White House should be worried about higher energy prices hurting them politically. An easy response would be to support domestic production which supports the U.S. economy. Having OPEC+ increase output does nothing to meet climate change goals.
- Recent fires in North Dakota are increasing calls for greater environmental rules on fracking in a region generally supportive to the activity.
- The administration is reviewing oil and gas drilling rules for northern Alaska.
- This week, the Senate held its amendment session for the upcoming budget. In general, this activity is an exercise in political posturing. The goal is to frame one party’s policies in a favorable light and make the opponent’s position unattractive. It’s mostly a gaming session, but occasionally some insights emerge into the leanings of senators. For example, an amendment to prevent the EPA from banning fracking picked up several Democratic Party votes. Another one to means test EV tax credits won narrowly. It is unlikely either will ever become law, but it does show where senators are leaning.
- NOAA is still calling for an active hurricane season. So far, the Atlantic has had seven named storms. NOAA is still projecting 15-21 named storms. Hurricane activity usually peaks on September 10.
Geopolitical news:
- Although the oil markets have not reacted to news items, recent attacks on Persian Gulf shipping could still lead to higher oil prices.
Alternative energy/policy news:
- China is close to testing a prototype thorium nuclear reactor. Thorium is an attractive alternative to uranium because its byproducts can’t be made into nuclear weapons material (in fact, that’s why it never caught on—the U.S. and U.S.S.R. wanted those warheads). Thorium reactors are expected to use molten fluoride or salt, eliminating the need for water. If nuclear power becomes widespread, thorium will likely be part of the mix.
- China has started to export its nuclear know-how, but foreign nations are somewhat uncomfortable dealing with Beijing.
- Coal is being rapidly replaced in U.S. electricity generation except among rural cooperatives.
- Environmental groups are starting to target insurance companies for providing coverage to fossil fuel companies.
- Canada is considering carbon tariffs; given USMCA and Canada’s own energy exports, it will be interesting to see how Ottawa pulls this off.
- Germany is testing a process of electrifying truck lanes to reduce truck emissions.
- As CO2 sequestration expands, users of the gas—beverage companies, for example—are struggling to find the gas for producing their products.
- Refiners are working to create cleaner aviation fuels. The process is complicated.
- Consumer product firms are starting to estimate how much carbon they emit when producing their products.
- For now, ranchers appear safe from tighter rules on methane.
View PDF
Weekly Geopolitical Report – August 15, 1971 (August 9, 2021)
by Bill O’Grady | PDF
Next week, we will observe the 50th anniversary of President Nixon’s decision to exit the Bretton Woods agreement. This choice was part of a broader package of policy actions designed to deal with a series of issues, including inflation, unemployment, and a balance of payments problem. As is often the case, the focus of attention from Nixon’s address to the nation was probably on the announced wage and price freeze. But, his decision to end the link to gold was monumental. We have discussed this issue before,[1] but in light of the impending anniversary, it seemed right to revisit it again.
This report begins with a review of the problems Nixon faced and how he addressed them. To put the issue into context, we examine two trilemmas: 1) Robert Mundell’s trilemma, which frames exchange rate, capital account, and monetary policy; and 2) Dana Rodrik’s trilemma, which analyzes the relations between global economic integration, domestic politics, and the nation-state. From there, we look at the world Nixon wrought, what remains, and what is struggling to be maintained. As always, we close with market ramifications.
[1] See WGRs, “Weaponizing the Dollar: Part I (8/12/2019) and Part II (8/19/2019).”
Asset Allocation Weekly – #48 (Posted 8/6/21)
Asset Allocation Weekly (August 6, 2021)
by the Asset Allocation Committee | PDF
In last week’s report, we updated our views on long-duration Treasuries, using our standard 10-year T-note model. This week we are going to examine the impact of policy on long-duration Treasuries.
First, let’s start with the model.
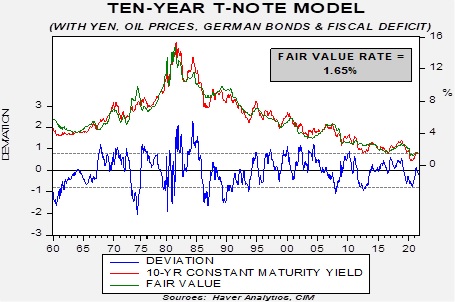
The two most important variables in the model are fed funds and the 15-year average of the yearly change in CPI. The latter acts as a proxy for inflation expectations. We add the yen’s exchange rate, oil prices, German Bund yields, and the fiscal deficit scaled to GDP. So, there are two policy variables in the model, fed funds and the fiscal deficit.
A truism that has developed in recent years is that divided government is good for financial markets because different parties in the White House and Congress means it is harder to enact major legislative changes. To test this thesis, we created a binary variable that signaled if one party controlled the legislature and the executive branch, or not. When we added the variable to the model, it was not statistically significant, nor did it change the model’s forecast.
Regression models are sensitive to initial conditions; simply put, where you start a model in time has a notable impact. Jim Bullard, the president of the St. Louis FRB, likes to think of eras with certain conditions as “regimes.” Applying Bullard’s notion of regimes, we next broke down the data by attitudes toward government. In other words, the truism that divided government was good for financial markets may not have always been true. To test this idea, we first ran the model from 1960 to 1982; attitudes toward the government were once positive. For the generation that lived through WWII, the government was not seen as an obstacle to overcome but as a support. The model did change; the government variable was statistically significant and showed that when the same party held both branches of government, yields were 50 bps lower. From 1983 to the present, the government variable was also statistically significant, but the sign changed. Unified government increased bond yields by 31 bps. We propose that the Reagan/Thatcher revolution changed the views of government compared to the earlier era.
Another interesting factor is that in the earlier regime, deficits were bearish for bonds; in other words, a deficit led to higher yields. In the current regime, deficits are less significant but the sign on the coefficient changed here as well. Deficits now lead to lower yields, although the impact is quite modest.
Finally, the model from 1983 has a current fair value of 1.70%, which is a bit higher than the full model shown above. Thus, its fair value is close enough to give us confidence that it is giving proper signals. The other important takeaway from this analysis is that if the Democrats lose one of the houses of Congress in November 2022, caeteris paribus, the fair value yield would decline by nearly 50 bps.
Weekly Geopolitical Report – Power, Influence, and Leadership in Geopolitics (August 2, 2021)
by Patrick Fearon-Hernandez, CFA | PDF
Xi Jinping. Donald Trump. Vladimir Putin. Ronald Reagan. Nelson Mandela. When it comes to understanding geopolitics, most of us probably focus on the powerful, visionary leaders who can drive events forward toward their goals. But few of us really try to think systematically about the characteristics that make a leader successful or the tactics he or she can use to shape the world. This report offers a framework for assessing foreign leaders’ power and prospects, based on a recent book on the science of influence. We show some of the ways we analyze political leaders’ ability to affect the geopolitical environment and, therefore, global investment prospects. The concepts discussed may even be useful in other aspects of life, from marketing to career development or personal relationships.
Asset Allocation Weekly – #47 (Posted 7/30/21)
Asset Allocation Weekly (July 30, 2021)
by the Asset Allocation Committee | PDF
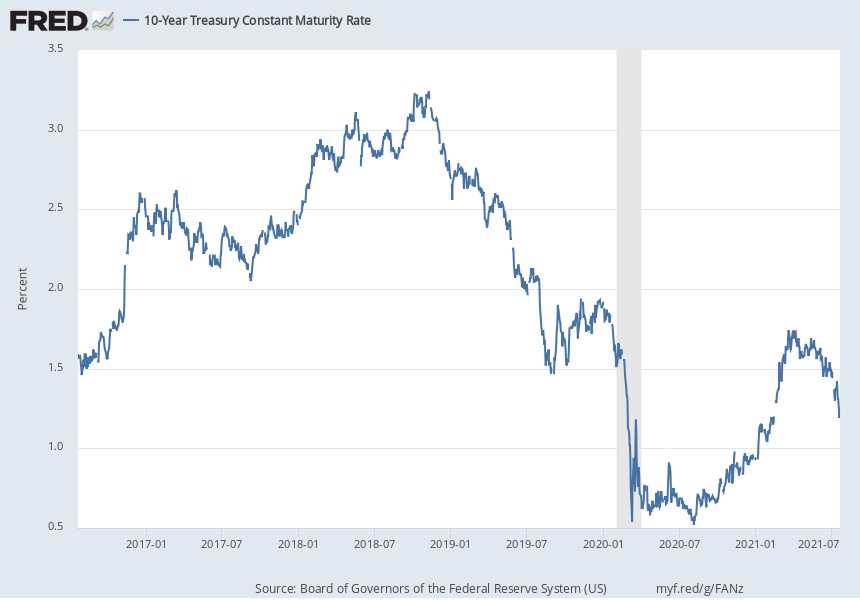
One of the key developments in financial markets recently has been the quick rebound in bond prices and the associated drop in yields. As investors started to sense faster economic growth and the prospect of rising inflation in the first quarter, they eagerly sold down their bond holdings, driving yields higher. The yield on the benchmark 10-year Treasury note jumped from 0.92% at the end of 2020 to an intraday high of more than 1.75% in late March (see following chart). Since then, however, bond buying has gradually strengthened again, and yields trended downward throughout the second quarter. Even when the Federal Reserve surprised markets in mid-June by hinting that the next interest rate hike might come by 2023, the resulting bond sell-off and yield jump was quickly reversed. In July, investors began buying bonds and driving down yields even faster, with the 10-year Treasury yield falling below 1.13% on July 19. This report looks at why yields are falling again and whether the downtrend is likely to continue.
It’s one thing to know where yields have been; it’s quite another thing to understand where they should be and where they may be going. To get at that issue, our bond model estimates where the 10-year Treasury yield should be based on several variables. The most important variables are the Fed’s “fed funds” interest rate and, as a proxy for inflation expectations, the 15-year average of the yearly change in the consumer price index (CPI). Other variables in our model include the yen/dollar exchange rate, oil prices, German Bund yields, and the U.S. fiscal deficit scaled to gross domestic product (GDP). As shown in the chart below, the jump on bond yields early this year merely brought the 10-year Treasury yield up to the fair value estimated by our model. With the recent rebound in bond prices, yields have again fallen below their fair value, which the model currently puts at 1.65%.
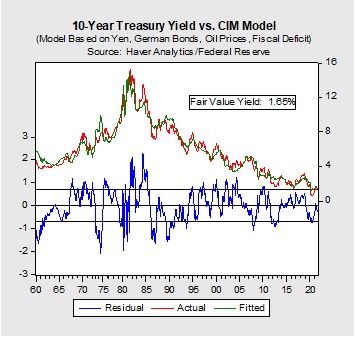
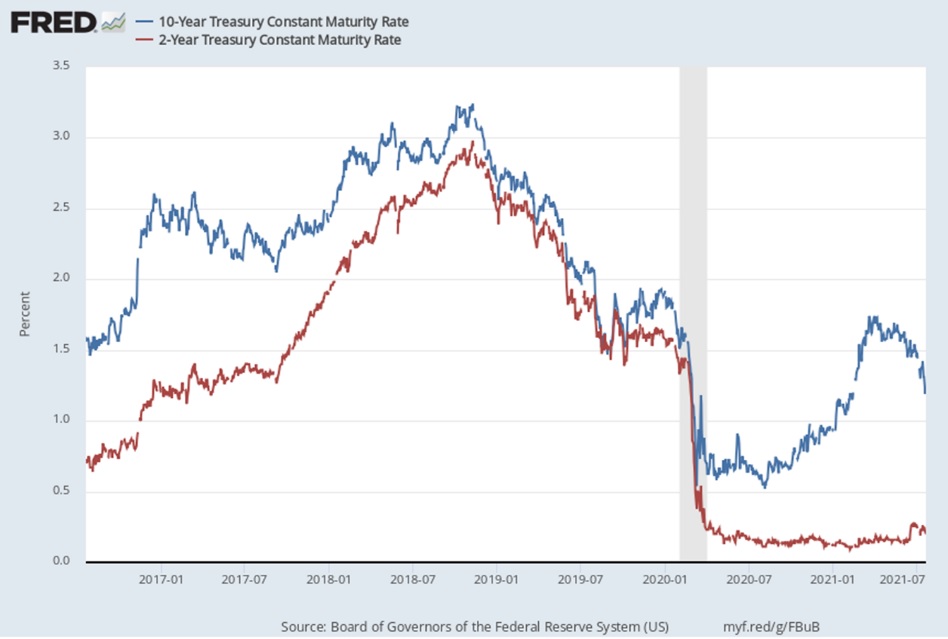
In other words, bonds once again look expensive―not as expensive as at the beginning of 2021, but enough to suggest bond investors see reason for caution regarding monetary policy and economic prospects. Many investors think the Fed will eventually tighten monetary policy just enough to smoothly bring down today’s high inflation rate. A less benign view among other investors is that the Fed might tighten policy too soon or too quickly. Those investors are worried about a policy mistake that could trip up the economic recovery and produce another recession. Still other investors think longstanding structural factors such as globalization and population aging will eventually reassert themselves and push down growth and inflation to the levels seen before the coronavirus pandemic. Such an environment of rising interest rates in the near term coupled with an eventual moderation in rates is consistent with the recent flattening in the yield curve. For example, the chart below shows how the yield curve, represented by the difference between the 10-year and the two-year Treasury rates, has changed recently.
In any case, we think our model’s call for higher interest rates should be respected, especially given the risk that inflation could stay high for longer than anticipated and gradually push up longer-term inflation expectations. We note that the 15-year average of CPI inflation that serves as a proxy for inflation expectations in our model is just under 1.90%. Other measures of inflation expectations, such as consumer surveys and the difference between nominal and inflation-protected bond yields, point to even higher future inflation. Even if the 10-year Treasury yield rebounds in the near term, we still believe it probably wouldn’t go much past 2.00%, but the risk of rising yields (and falling bond prices) has prompted us to reduce our exposure to longer-term bonds in several of our strategies for the third quarter.