


Keller Quarterly (January 2016)

Letter to Investors

The turning of the annual calendar occasions all sorts of prognostications in our profession.  We prefer not to think in terms of forecasts, but rather in terms of probable scenarios. All sorts of things are possible in 2016, but not all scenarios are equally probable.  For example, a great many purveyors of gloom and doom are forecasting that the U.S. dollar will cease to be the world’s primary reserve currency in the near future.  These prognosticators speak of it as an inevitability and trouble the souls of many with the supposed dire results (although I believe they misinterpret the implications of such an event). The issue is not that this event is not possible (it is), but that it is of very low probability.  In fact, we regard the probability of that occurrence as extremely low, not just within the next year, but within the next several decades.

There are a great many negative scenarios one may construct for the coming year, but those we need to be on guard for are those that have some real probability attached to them.  In October I wrote to you that there were three problems that really matter to investment portfolios: 1) high levels of consumer debt, 2) decelerating growth in China and the emerging markets, and 3) Federal Reserve (Fed) intentions to raise short-term interest rates.  Since then, the third concern has shot to the top of the list.

In December the Fed raised the fed funds rate by 0.25% and indicated it has plans to raise it further.  The U.S. economy is growing slowly and foreign economies are struggling due largely to the first two problems listed above. With growth sluggish and inflation very low, we are concerned that the Fed is committing an unforced error. Unlike the hand-wringing we see about the dollar’s reserve status, this is a potential problem that has real probability.  A single quarter-point increase won’t slow the economy dramatically all by itself, but markets have a way of compressing into the present what they think will happen in the future.  If longer term interest rates, which are set by the market, not the Fed, rise too quickly, the economy could stagger.  Thus, what is important is not that the Fed raised rates a little, but what the market thinks their intentions are for the future.  Here the Fed may be able to moderate the effects of its error by being very slow to raise rates in the future, or maybe by stopping the tightening process altogether. We still regard the likelihood of recession in the next year or two as small, but we are vigilant in our reconnaissance.

How does an investor protect his or her portfolio from such risks? There is no such thing as portfolio insurance, but it is possible to soften exposure to business cycle risk and interest rate risk in the construction of portfolios.  Our job as investment managers is not to “bury your money in a coffee can in the back yard,” but to take the steps we believe promote reasonable returns for your portfolio in the light of the negative scenarios that may have a measure of probability.

Each year starts with both promise and trepidation.  But, as we’ve noted before, “Worrying is a major part of the job.”

As always, we appreciate your confidence.


Gratefully,

Mark A. Keller, CFA
CEO and Chief Investment Officer
View the PDF

Weekly Geopolitical Report – The 2016 Geopolitical Outlook (December 14, 2015)

by Bill O’Grady

As is our custom, we close out the current year with our outlook for the next one.  This report is less a series of predictions as it is a list of potential geopolitical issues that we believe will dominate the international landscape in the upcoming year.  It is not designed to be exhaustive; instead, it focuses on the “big picture” conditions that we believe will affect policy and markets going forward.  They are listed in order of importance.

Issue #1: The Election Transition

Issue #2: Western Populism

Issue #3: Small-Scale Islamic Terrorism

Issue #4: The Weakening of the European Union

Issue #5: Trouble in the South China Sea

View the full report

Weekly Geopolitical Report – The Evolution of IS (December 7, 2015)

by Bill O’Grady

An Islamic State (IS) affiliate downed Russian Metrojet Flight 9268 in October.  In November, IS-affiliated terrorists launched a series of attacks in Paris.  These two events suggest a significant change in the behavior of IS.  Prior to the Paris attacks, IS appeared to be focused on building a caliphate in Syria and Iraq.  The shift to terrorist acts suggests a new strategy.

In this report, we will recap the two strategies radical jihadists have employed against the West, highlighting the differences between al Qaeda and IS.  We will examine the current stalemate that exists in the area IS currently controls and how IS may adjust its future strategy.  As always, we will conclude with potential market effects.

View the full report

2016 Outlook (November 30, 2015)

by Bill O’Grady & Mark Keller | PDF

In this report, we will offer our outlook for the upcoming year.  Twenty-sixteen could be an interesting year—presidential elections will be held, the Federal Reserve could tighten monetary policy and the geopolitical landscape will likely remain complicated.  We will begin the report with our base case for the economy, equities, debt markets, the dollar and commodities.  From there, we will examine the “known unknowns,” which could undermine our base case.

Summary: Our Base Case

  • No recession in 2016.
  • Slow economic growth, low inflation.
  • An S&P 500 of 2214.39, based on earnings of $121.67 and a P/E of 18.2x. If our forecast undershoots the market, it will likely be due to further multiple expansion.  We would only consider foreign developed for risk-tolerant accounts and continue to avoid emerging equities.
  • The 10-year Treasury yield should be in a range of 1.90% to 2.25%. Corporate spreads should contract.
  • We expect the dollar will remain strong and commodity prices will be weak.

Our Key “Known Unknowns”

  • Monetary Policy
  • The Global Economy
  • The Upcoming Election
  • Geopolitics

Read the full report

Weekly Geopolitical Report – Putin and Flight 9268 (November 23, 2015)

by Bill O’Grady

On October 31st, Russian Metrojet Flight 9268 took off from Sharm el-Sheikh, Egypt, at 5:58 local time en route to St. Petersburg, Russia.  Within 25 minutes, the aircraft, an Airbus A321, disappeared from radar over central Sinai.  By the time radar contact was lost, the aircraft had reached its cruising altitude of 33,000 feet.  Shortly thereafter, airplane debris was reported over the area.  All 224 passengers and crew were lost, making it the worst Russian civilian air disaster in history.

In this report, we will examine the potential causes of this event.  Given that a terrorist group may be the culprit, we will discuss the most likely perpetrator.  Next, we will analyze how Russian President Putin will likely react to this event.  As always, we will close with potential market ramifications.

View the full report

Quarterly Energy Comment (November 18, 2015)

by Bill O’Grady

The Market

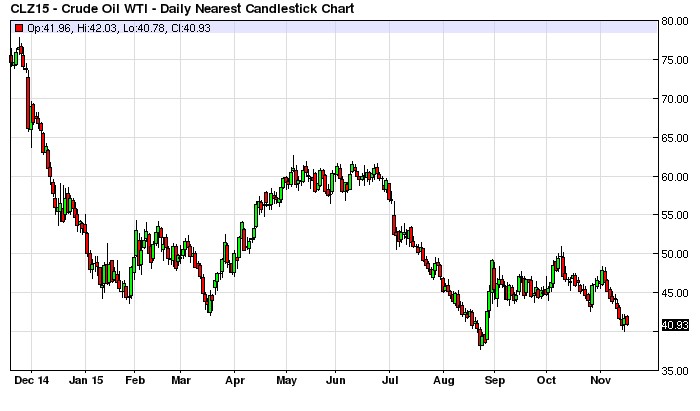
Over the past year, oil prices fell sharply into the first quarter, remained rangebound from January through March, rallied above $60 per barrel in the spring and early summer, and then slid to new lows in August.  Since the August lows, prices have been in a range between the high $30s and $50 per barrel.  In November, prices have been weak, testing the low end of the trading range.

(Source: Barchart.com)

It is not unusual for prices to rally into year’s end due to the rise in holiday driving and cold weather.  The latter can lift heating oil demand and refining activity.  We still expect a rally to develop into New Year’s but it probably won’t move prices much above $50 per barrel.

A much bigger worry for prices develops in early 2016.  Refinery maintenance begins soon after the New Year which will depress demand.  If production levels remain elevated, prices are vulnerable to breaking into the $30s in early spring.

View the complete PDF

Weekly Geopolitical Report – Political Turmoil in Portugal (November 16, 2015)

by Kaisa Stucke, CFA

Portugal held parliamentary elections on October 4, 2015, in which the incumbent center-right Social Democratic Party received the most votes but fell short of an outright majority.  Historically, as part of the Portuguese political process, the country’s president tasks the party that receives the most votes with forming a government.  However, in this case, the center-left opposition party and some far-left parties have formed a coalition, together garnering a majority of votes and currently awaiting presidential approval to form a government and take control from the center-right party.

This week, we will look at the current political environment in Portugal.  First, we will start with a brief history of Portugal.  We will then turn to the economic conditions leading up to the most recent elections and discuss the election results, the change in coalition powers and the possible path of developments going forward.  As always, we will conclude with market ramifications.

View the full report

Weekly Geopolitical Report – EU Migrant Crisis: Focus on Hungary (November 2, 2015)

by Kaisa Stucke, CFA

There is no doubt that the EU migrant crisis is a catastrophe in terms of human costs.  It is fairly evident that the EU was not prepared to deal with the magnitude of migrant movement into the region.  This crisis also presents a political dilemma for Europe and may lead to the re-establishment of border controls, intensify internal schisms over the extent of sovereign/EU authority and possibly sow the seeds of the dissolution of the EU.

Migrant flows from the Middle East and Africa have affected European countries unevenly.  The border countries have received heavy inflows of migrants, some of whom wish to stay in those countries, but most continue on to Germany and Sweden, which have indicated openness to accepting immigrants.  However, many countries are not open to taking immigrants, either due to a lack of ability or willingness.  Each of these countries is dealing with the flow of asylum-seekers differently as their approach is determined by relative economic wealth, number of immigrants and societal structure.

Hungary has received an overwhelming number of immigrants due to its location on the main migrant routes to Germany and Sweden.  The large number of immigrants, both in absolute terms and relative to Hungary’s population, has overwhelmed the country’s refugee facilities.  Hungary has indicated that it cannot accept all refugees without a clear plan from Brussels and has tried various tactics to control the immigration flow, from erecting a 108-mile barbed wire fence to simply facilitating refugee transportation to the Austrian border.

This week, we will look at how Hungary is handling the immigrant crisis and what its actions may signal for other European countries.  We will start by looking at Hungary’s history and its position at the crossroads of empires which have shaped Hungary into a country that often directs a changing tide for Europe.  As always, we will conclude with geopolitical and market ramifications.

View the full report

Weekly Geopolitical Report – The Obama Doctrine: Moneyball America (October 26, 2015)

by Bill O’Grady

Over the past three years, we have witnessed what appears to be a steady erosion of American power.  Russia annexed the Crimea and has encouraged a rebellion in eastern Ukraine, undermining the sovereignty of a European nation.  This apparent invasion was considered by Western observers to be the first hostile acquisition of territory since WWII.

The breakdown in the Middle East has become another problem.  The U.S. allowed the Arab Spring to unfold with little interference; to some extent, the administration encouraged the developments.  The U.S. took a secondary role when intervening in Libya, allowing France and Britain to lead operations.  That action has devolved into a disaster; Libya stands divided as various ethnic and sectarian groups fight for control.  Syria has become a major problem as well.  The administration has pressed for the removal of Syrian President Assad but hasn’t created conditions to foster his exit.  The decision not to bomb Syria after Assad used chemical weapons, a self-proclaimed “red line” by President Obama, further gave the impression of disengagement.

Russia’s recent decision to send military equipment and personnel to Syria suggests that Putin is filling a power vacuum in the region.  Sunni allies in the region are becoming increasingly concerned that the U.S. is not going to continue to play the role of outside stabilizer in the region.

Yet, the Obama administration recently announced that it would send U.S. Naval vessels within 12 miles of the artificial islands that China is building in the South China Sea.  Although military advisors have been pushing for such incursions for some time, the president’s decision to take this rather aggressive step is in direct contrast to the passive response seen in other areas of the world.

In this report, we will examine President Obama’s foreign policy, using the construct of Ian Bremmer’s recent book, Superpower.[1]  After discussing President Obama’s foreign policy and the potential effects, we will examine how the next president may shift from the current policy.  As always, we will conclude with potential market ramifications.

View the full report

____________________

[1] Bremmer, Ian. (2015). Superpower: Three Choices for America’s Role in the World. New York, NY: Penguin Publishing, Random House.