Asset Allocation Bi-Weekly – The Euro vs. the Swiss Franc (October 19, 2026)

by Patrick Fearon-Hernandez, CFA | PDF

While investors in the United States have been understandably focused on the jump in US bond yields this autumn, it’s important to remember that yields have risen in most major foreign countries. Like other observers, we see many potential reasons for the run-up in rates, including concerns about higher consumer price inflation because of the US-Israeli war against Iran, unexpectedly strong economic growth in the US, and massive demand for capital by firms working on artificial intelligence. Other potential drivers include growing doubts about the credibility of key central banks and fears that rising government budget deficits and debt loads in the US and beyond could lead to sovereign defaults or financial repression (artificially holding down bond yields). Finally, some observers argue that the rise in yields is just a normalization process that will bring rates back up to their long-run norms after they were artificially suppressed during and following the Great Financial Crisis.

The rise in government bond yields has been especially sharp in France. Of all the problems that could be pushing up yields, rising deficits and debt loads are probably the most concerning in France, where the budget deficit has reached more than 5% of gross domestic product and the public debt burden is marching toward 100% of GDP. Those metrics would be much less alarming in a more dynamic, faster-growing economy such as that of the US. But for France, they are becoming much more worrisome for investors. Moreover, political gridlock in the French parliament suggests the government cannot soon implement the austerity program that would probably be needed to bring the debt under control and ensure its obligations are met. That problem is increasingly seen as a possible sign that France could pull out of the eurozone to gain the policy flexibility it needs to address its difficulties. And, of course, the issues in France could point to similar challenges elsewhere in the eurozone. Logically, these fears have started to weigh on the value of the euro.

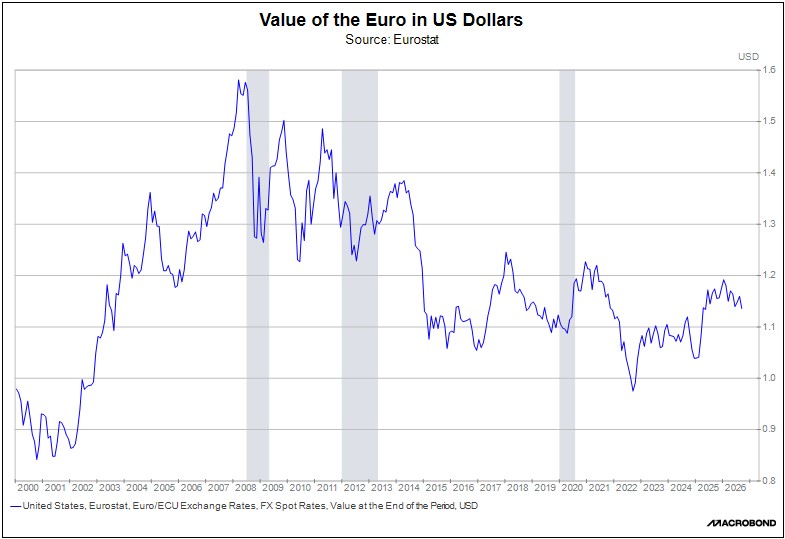
The chart below shows one way to gauge the softening of the euro this year. Over that period,  the value of the euro in dollar terms fell from $1.1919 at the end of January to just $1.1355 at the end of September, for a decline of 4.7%. However, from a longer perspective, the euro-dollar exchange rate doesn’t look so out of line. The euro has actually been significantly weaker against the dollar for most of the last decade.
We think a more telling comparison is the value of the euro versus the value of the Swiss franc. After all, Switzerland sits at the very center of Europe, literally surrounded by the eurozone. Switzerland’s economy is much closer to that of the eurozone in structure, policy, and trading relationships than the US’s, but it is widely seen as a more dynamic, better run economy. As a result, the Swiss franc has long been viewed as a safe haven. So, how has the euro performed against this benchmark?

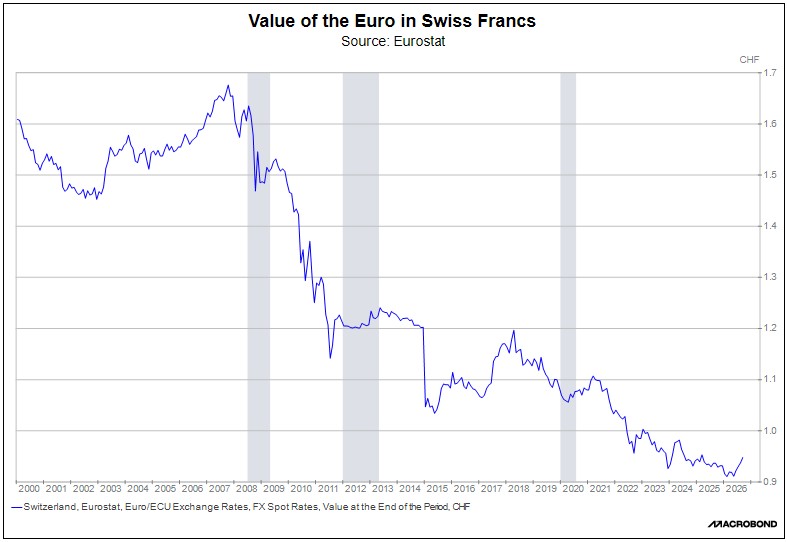
The chart on the next page shows the value of the euro in terms of Swiss francs. Comparing the euro to this key European peer currency, we see that it has actually been losing relative value for almost two decades. The long downtrend in the euro versus the franc is especially notable given that Switzerland’s benchmark short-term interest rate is essentially 0%, while its longer-term bond yields are significantly lower than those of not only France but even Germany. While Switzerland has occasionally adopted unorthodox economic policies, it still sports an unusually stable environment compared with the eurozone, including a strong fiscal position and low inflation.

In sum, the almost uninterrupted slide in the value of the euro versus its key European peer, the Swiss franc, points to longstanding investor concern about the viability of the eurozone. This doesn’t mean that a breakup of the eurozone is set in stone, and it doesn’t suggest a breakup is imminent. Indeed, as shown at the far right of the chart, the euro has actually appreciated versus the franc in recent months. All the same, we think the ongoing downtrend in the euro-franc exchange rate is a reminder to be cautious about the single currency and eurozone assets, including bonds and stocks.
View PDF

Don’t miss our accompanying podcasts, available on our website and most podcast platforms: Apple | Spotify 

Weekly Geopolitical Report – AUKUS (October 11, 2021)

by Bill O’Grady | PDF

On September 15, the leaders of the U.S., U.K., and Australia announced a new security relationship which includes a nuclear submarine arrangement with Australia.  Although it will likely take a couple of decades before Australia will have its own indigenous nuclear propulsion vessels, the treaty means that the U.S. and U.K. will likely begin sharing nuclear technology and other weapons systems.

The announcement not only marked the beginning of a new security relationship in Asia for the U.S. and U.K., but it also marked the end of another one, a $60 billion defense arrangement that France had with Canberra.  France had previously agreed to provide Australia with diesel/battery submarines, but this new deal scuttled the French arrangement.  The French were incensed; ambassadors were recalled, and European governments denounced the new arrangement.

It is not a huge surprise that the French were upset, but the degree of the reaction seemed strong given the violation.  Diesel submarines pale in comparison to the capabilities of nuclear propulsion.  The former is only useful in coastal protection.   They need to resurface to use the diesel engines to recharge batteries; during this period, they are vulnerable to attack.  They also require regular refueling.  Nuclear submarines don’t need to resurface and can extend their patrol range significantly compared to a diesel-powered vessel.  When the deal was made in 2016, diesel subs may have been adequate for the risks Australia perceived.  That is no longer the case.  So, it should have come as no surprise that Australia would consider an upgrade.  Although France has nuclear propulsion technology, it is not as effective as American technology.

The U.S. decision to create this new security arrangement, Australia’s acceptance, the U.K. decision to join, and the reaction of France all reflect an evolving geopolitical situation in Asia.  In this report, we will discuss why the three nations decided to create a new pact.  From there, we will offer a short geopolitical analysis of Europe, followed by an examination of the French and European reactions.  We will close with market ramifications.

Read the full report

Weekly Geopolitical Report – The Geopolitics of the Eurobond (June 29, 2020)

by Bill O’Grady | PDF

(N.B.  Due to the Independence Day holiday, the next report will be published on July 13.)

A global hegemon provides two broad categories of public goods.  The first is security.  A successful hegemon enforces some degree of global security as it has the ability to project power globally.  This power projection ostensibly prevents regional wars from becoming world wars.  Another way of thinking about hegemony is that if a world war occurs, it is evidence of hegemonic failure.  In addition to war suppression, the hegemon’s global reach gives it the capability to secure sea lanes, which facilitates global trade.

The second public good is financial.  The hegemon provides the reserve currency which enables global trade and investment.  The reserve currency nation must have two characteristics to be a successful provider of the reserve currency.  First, it must be willing to run persistent current account deficits.  It is through trade that the rest of the world acquires the reserve currency. Persistent current account deficits put great strain on the labor markets of the hegemon and require a strong commitment from the reserve currency nation to absorb these imports.  Second, it must have deep financial markets and an instrument that is considered safe and widely available so nations that accumulate the reserve currency can use this instrument to hold this saving until it is needed for trade or direct investment.

If the U.S. is going to be replaced as a hegemon, the successor will need to fill these two roles.  Currently, there is no nation that is capable or willing to fully provide these public goods.  However, it is not impossible to consider a situation where a partial replacement occurs.  Such outcomes have occurred before.  By the late 1800s, Britain realized that it could not defend any of its colonies in the Western Hemisphere from a determined American attack.  The U.S. economy was too well developed and its navy and army too large; the costs of defending Canada, for example, would have been excessive.  So, quietly, the British ceded regional hegemony, at least in terms of security, to the U.S.  That allowed Westminster to focus on the other growing threat, Germany.  In the current environment, the U.S. could cede a sphere of influence to China.  It is arguable that the U.S. would like to see a regional hegemon arise in the Middle East to allow America to reduce its security burden there as well.

Something similar could occur on the reserve currency front as well.  Some economists, notably Barry Eichengreen, have argued that there is the potential for multiple reserve currencies.  Although we have had doubts about this possibility, recent developments have led us to consider the possibility that the euro could become a serious competitor for the dollar as a reserve asset.  That doesn’t mean the euro would replace the dollar as the reserve currency, but it would mean the euro could be a parallel reserve currency and offer competition to the dollar.

The most recent development that could create potential competition for the dollar’s reserve status is the proposed new financial instrument designed to fund Europe’s recovery from the pandemic.  The proposal evolved from a plan developed by Germany and France to create a €500 billion recovery fund.  European Commission President Ursula von der Leyen expanded the proposal, increasing it to €750 billion.  But the key element of the proposal is a specific bond backed by the full faith and credit of the European Union.  The bond service would be tied to several EU-wide revenue sources, including a proposed digital tax, a carbon border tax and fees on transportation.

The proposed plan still requires approval by all members of the EU.  The “frugal four”—Austria, Denmark, the Netherlands and Sweden—could still scuttle the proposal.  But, Germany’s support is a reversal of its longstanding opposition to EU debt mutualization and will probably be enough to sway the opposition toward accepting the program.

The prospect of debt mutualization creates competition for the dollar’s reserve status.  The EU doesn’t fulfill the other requirements for hegemony; its military strength has atrophied, and it has not shown a willingness to run persistent current account deficits.  Nevertheless, a mutualized debt instrument does make the euro a much more attractive currency for reserve purposes.

In this report, we will examine why an alternative reserve currency might be attractive for several countries.  An analysis of why Germany has changed its position on debt mutualization will follow.  As always, we will conclude with market ramifications.

Read the full report

Weekly Geopolitical Report – Schumann in Volgograd (May 11, 2020)

by Patrick Fearon-Hernandez, CFA

If you ever find yourself in Volgograd, Russia, you will visit Rodina Mat’ Zovyot.  It’s unavoidable.  The statue, depicting Mother Russia calling her sons to battle against her invaders, is one of the tallest in the world.  Standing almost 280 feet high, she is nearly twice as tall as the Statue of Liberty.  Her colossal height is accentuated by her position at the summit of Mamayev Kurgan, the high ground overlooking Volgograd, whose great, grassy green slopes were fertilized by the blood of a quarter-million Soviet soldiers who died defending it from the invading Nazis during World War II, when the city was still known as Stalingrad.

You never know when you’re about to have an experience that will stay in your memory, and haunt you, for the rest of your life.  Such was the moment when I first entered the glittering round chamber below the statue, where an eternal flame keeps alive the memory of the 20 million or so Russians who died in the war.  I entered just at the beginning of the ceremony marking the changing of the guard.  Young Russian soldiers in ill-fitting uniforms and black jack boots marched in painfully slow goose steps up the ramp around the perimeter of the chamber to relieve the previous sentries of their duty.  It was impressive in the extreme.  But, more than anything, I remember the haunting, plaintive choral music playing in the background (see this video).  It perfectly expressed the quiet calm and peace that all who suffer in war must yearn for, if only in death.  But when I asked my guide what the song was, I was flabbergasted by her reply: “Daydreams, by Schumann.”

What?! A Russian World War II memorial playing the music of a German composer?  How could it be?

View the full report

Weekly Geopolitical Report – Could the Coronavirus Pandemic Break Up the EU? – Part II (April 6, 2020)

by Patrick Fearon-Hernandez, CFA

(Note: Due to the Easter holiday, our next report will be published on April 20.)

In Part I of this report we examined the history of the European Union (EU), how it works, and the political, economic, and social fissures that had already rendered it unstable when the COVID-19 pandemic took hold.  This week, we look at several recent policy moves that various EU countries have taken in response to the pandemic, and we explain why those policy moves could potentially push the EU over the tipping point toward disintegration if they are carried too far.  As always, we’ll wrap up with a discussion of the possible economic consequences of a break-up and the ramifications for investors.

The Temptation to Barricade
As we discussed in Part I, the founders of the EU believed that preventing another major war on European soil could be accomplished, in part, by an “ever-closer union among the peoples of Europe.”  The EU is often seen mostly as an economic arrangement (i.e., a customs union coupled with a free-trade area), but its founding principles are broader than that.  The EU aspires to the free movement of virtually all people, goods, services, and capital.  Unfortunately, the COVID-19 pandemic has tempted EU leaders to erect barriers in these areas.

View the full report

Weekly Geopolitical Report – Could the Coronavirus Pandemic Break Up the EU? – Part I (March 30, 2020)

by Patrick Fearon-Hernandez, CFA

In times of crisis, the future is a luxury.  Or, at least, thinking about the future can seem like a luxury, especially if you’re reeling from the death of a loved one, the loss of a job, the devastation of a retirement portfolio, or just the boredom and isolation of a quarantine.  Many people are overwhelmed with those challenges in the midst of the COVID-19 pandemic.  And yet the pandemic is changing the future course of the world in ways that we’ll all need to understand and respond to eventually.  Those future changes extend to politics and geopolitical relations.

In this report, we explore the recent signs suggesting the COVID-19 pandemic could potentially lead to a break-up of the European Union (EU).  In Part I, we examine the history of the EU, how it works, and the political and social fissures that undermine its stability.  In Part II next week, we will look at the recent policy moves by various EU countries that could lead to disintegration if carried too far.  We’ll wrap up with a discussion of the possible economic consequences of a break-up and the ramifications for investors.

View the full report

Weekly Geopolitical Report – Reflections on Nationalism: Part III (September 11, 2017)

by Bill O’Grady

Three weeks ago, we began our series on nationalism.  In Part I, we discussed social contract theory before and after the Enlightenment.  We examined three social contract theorists, Thomas Hobbes, John Locke and Jean-Jacques Rousseau.  In Part II, we recounted Western history from the American and French Revolutions into WWII.  From there, we examined America’s exercise of hegemony and the key lessons learned from the interwar period.  This week, we will begin with an historical analysis of the end of the Cold War and the difficulties that have developed in terms of the post-WWII consensus and current problems.  We will discuss the tensions between the U.S. superpower role and the domestic problems we face.  Next, we will analyze populism, including its rise and the dangers inherent in it.  As always, we will conclude with market ramifications.

View the full report