Tag: buybacks
Asset Allocation Bi-Weekly – Breaking the Bond Fever! (September 21, 2026)
by Thomas Wash | PDF
After months of rising long-term yields, Treasury Secretary Scott Bessent has intervened in the bond market to help calm what he describes as a “fever.” The move reflects growing concern within the administration that fear has outweighed fundamentals in bond valuations, as investors grapple with rising energy costs tied to Middle East uncertainty and a growing US debt burden.
Earlier this month, the US Treasury Department announced plans to buy back up to $6 billion in long-dated securities, well above the $2 billion operation communicated to the market on August 19. The larger purchase underscores Secretary Bessent’s effort to dampen market volatility. Even so, Treasury’s more active role in the bond market has tested investors’ willingness to take Bessent’s guidance at face value. This uneasiness comes as the department seeks to manage the government’s expanding fiscal debt burden.
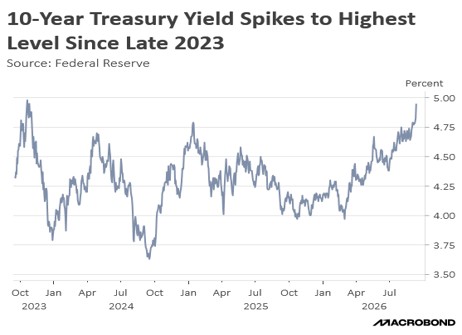
The announcement was poorly received by the market. Treasury securities sold off immediately, driving the 10-year yield to 4.85%, its highest level since November 2023. That rise was likely the opposite of what Bessent intended — the buyback had been meant to calm the bond market, not intensify the selloff. While some of this divergence was likely due to rising concern in the Middle East, it also seems to highlight the difficult task facing the Treasury as it continues to work towards steadying market conditions and exerting greater influence over borrowing costs.
The Treasury’s decision to expand its bond buybacks came amid ongoing debate over the market’s equilibrium price. Secretary Bessent noted that the intervention aimed to counteract market sentiment that would have prevented bond prices from reaching equilibrium. By removing discounted off-the-run bonds, the buybacks were intended to improve market liquidity and free up balance sheets, enabling banks and corporations to participate more actively in auctions.
Although Treasury buybacks have recently gained significant attention, the program has been in operation since 2024. When former Secretary Janet Yellen launched the initiative, it was designed to shift issuance toward shorter maturities, redirecting liquidity from the Federal Reserve’s overnight reverse repo facility into Treasury bills to ease funding stress and suppress term yields. This strategy served as a temporary bridge while awaiting central bank rate cuts, after which the Treasury could resume extending debt duration at lower interest rates.
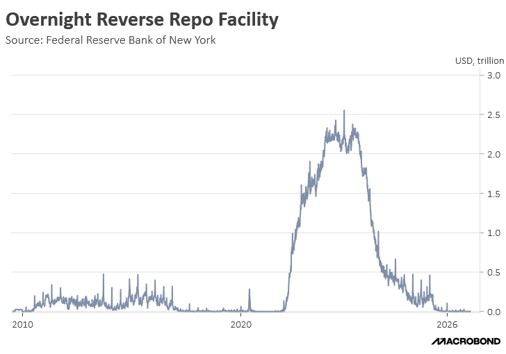
Secretary Bessent faces a similar market environment, albeit without the buffer of excess cash in the reverse repurchase facility. In its place, Bessent has been able to rely on the expansion of the Fed’s balance sheet through its reserve management purchases, which have allowed the Fed to buy Treasury bills. This policy action has accommodated the Treasury’s effort to rotate out of longer-dated bonds and into shorter-duration securities without adding to funding stress.
The effects on the market from the shift in Treasury issuance are most evident in auction results. The chart below shows the 12-month moving average of auction “tails” and “throughs.” An auction tails when the stop-out yield is higher than the prevailing when-issued yield, signaling softer-than-expected demand; it stops through when the stop-out yield is lower, indicating stronger demand.
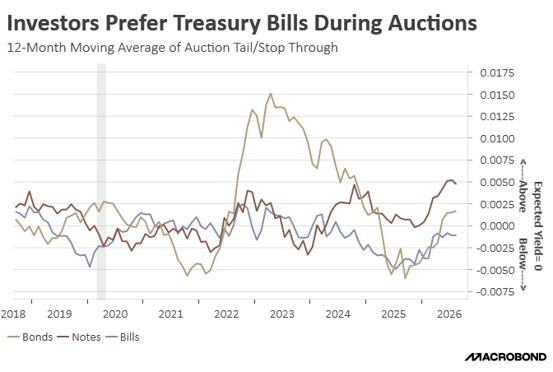
The Treasury’s decision under Secretary Yellen to tilt issuance toward shorter maturities occurred when auction results were showing signs of investor resistance, particularly at longer maturities. Although auction performance has generally been more stable under Secretary Bessent, the Treasury appears to be taking preemptive steps to prevent longer-dated supply from again encountering meaningful demand pressure.
Similar to former Secretary Yellen’s approach, Secretary Bessent’s expanded buyback strategy serves as a temporary bridge to mitigate upward pressure on yields. The Treasury is likely using these buybacks to facilitate a reallocation of its overall issuance composition, aiming to contain borrowing costs elevated by geopolitical tensions with Iran that have driven up inflation expectations and term premiums. Assuming the conflict eases — an outcome the White House suggests could materialize following the midterms — the Treasury is expected to scale back its active market interventions gradually.
If this thesis holds, while interest rates will probably remain elevated over the next few months, yields may not rise materially above current levels. Consequently, this environment could present an attractive entry point for investors seeking to extend duration. Over the long term, however, total returns for fixed income will remain tied to achieving price stability and seeing credible fiscal progress, whether through spending restraint or accelerated economic growth.
Don’t miss our accompanying podcasts, available on our website and most podcast platforms: Apple | Spotify
Asset Allocation Bi-Weekly – The Impact of New Equity Supply (August 31, 2026)
by Bill O’Grady | PDF
In November 1982, the Securities and Exchange Commission (SEC) changed its position on stock buybacks. Prior to this change, the SEC held that buybacks were potentially market manipulation. They weren’t directly banned, but companies buying back their stock ran the risk of being sanctioned for manipulation. In 1982, the SEC decided it needed to clarify its position on buybacks with the introduction of Rule 10b-18, which codified safe harbor requirements for buybacks. Specifically, firms buying back their stock are required to meet the following conditions:
- Use a single broker or dealer per day to bid for or purchase their stock;
- Abide by certain timing restrictions intended to prevent companies from establishing either the opening or closing price of their stock;
- Not offer a price exceeding the highest independent bid or the last independent transaction price on the relevant exchange, whichever is higher; and
- Limit daily repurchases to 25% of the average daily trading volume of their securities during the previous month.
Companies can reward shareholders primarily through dividends or buybacks. The former are simply a cash payment for holding the shares. Unfortunately, they are less tax efficient. Not only do dividend payments stem from after-tax corporate earnings, but the shareholder pays income tax on them as well. Thus, they are “double taxed.” In contrast, buybacks aren’t taxed at all, and by reducing the shares outstanding, all else held equal, one would expect them to push the share price higher.
The chart on the next page, from the Federal Reserve’s Financial Accounts of the United States, measures quarterly share flow for the non-financial corporate sector over many decades. In any given quarter, a positive number indicates more shares were issued than extinguished, and vice versa. The chart shows that before the SEC rule change in 1982, only 19% of quarters registered negative flows. After the rule change, this number jumped to 81%.
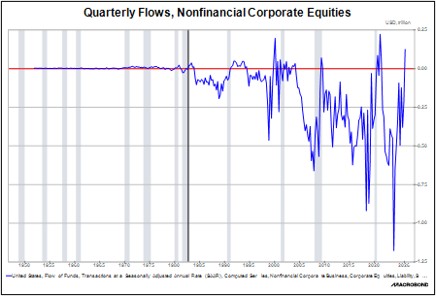
Due in part to their favorable tax treatment, buybacks became the preferred way to reward shareholders, but another factor had to do with the allocation of power between management and owners. After the Great Depression, there was a bias in corporate governance in favor of labor. Management theorists lamented that management didn’t represent the interests of owners. The change in buyback regulation coincided with the concept of shareholder primacy, which argued that publicly traded firms should focus on shareholder returns over other interests. Senior managers and, over time, other workers were partly paid in shares, aligning management with owners. Persistent buybacks became an element of shareholder primacy.
In the next chart, we’ve aggregated the flows data (blue) to show the accumulated buybacks over time. We’ve also overlayed that data with the S&P 500 price index (pink).
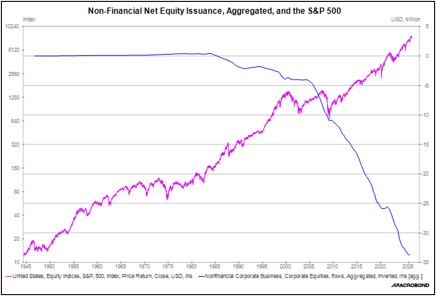
The trends in both series are rather obvious, but after the Great Financial Crisis, buybacks played an increasing role in supporting stock prices. It’s worth noting that in periods where cumulative buybacks slowed, the market stalled. That’s important now because the funding needs for artificial intelligence investment are leading to increased equity issuance, as the first chart shows. This new stock issuance will almost certainly increase in the coming quarters. For instance, the recent initial public offering (IPO) for SpaceX isn’t recorded in this data yet. The expected IPOs of Anthropic and OpenAI will likely lift issuance even further.
This analysis doesn’t necessarily mean a bear market is looming. However, it does indicate that equity markets could face headwinds in the coming quarters as more firms issue stock to fund their AI investment needs. We therefore think that diversifying into neglected areas of the equity markets, such as value and international, would offer some degree of protection from projected overall market weakness.